Marine Fuels…
What Actually Moves World Trade
Dr. Lars Schernikau
Our modern economies depend on physical goods moving across borders with around 80% of world trade (by volume), and an estimated 70% (by value) that travels by sea [1]. Shipping keeps global trade moving and is therefore the lifeblood of trade as much as currencies are.
We argue that shipping is much more than just a cost item on a factory’s income statement, because when the cost of moving goods around the globe rises, you see it on your supermarket bill within a year.
This blog post is therefore relevant well beyond just the maritime industry.
One summary point upfront: Without regulatory clarity and stability, the maritime industry can’t invest with confidence, and the result is more expensive, less reliable transport for the goods we all depend on.… Haven’t we heard that from other industries before?
This article would not have been possible without the detailed input and support from Gareth Williamson, a marine fuel market specialist and executive at HMS Bergbau Group.
Figure 1: Thousands of vessel moving billions of tons
- Thousands of vessel moving billions of tons
An estimated 115,000 vessels with a total deadweight (DWT) capacity of ~2.5 billion tons (Bln) carries more than 80% of world goods trade volume. Just for clarity, these are vessels above 100GT (gross tonnage) [2] and exclude fishing boats, yachts, and military vessels. FYI, if you include fishing boats the figure will run into the millions, if you include yachts you will get to 8-digit figures.
What might be more interesting is the actual breakdown by type and size of vessel usually measured in dead weight tonnage (DWT). DWT is how much weight a ship can carry in the form of cargo, fuel, water, crew and provision excluding the weight of the ship itself. In this case we consider larger vessels that carry cargo and consume a substantial amount of fuel.
Let’s focus on the ~60,000 ships of 1,000 GT and above, both cargo and non-cargo, holding nearly all of the fleet’s 2.5 billion DWT and burn the vast majority of marine fuel.
You may remember from my previous blog articles that humanity extracts roughly 110 billion tons (Bt) of resources [3] from planet Earth, everything from iron ore to sand to timber… for our daily consumption. Out of that mountain of material, almost 13 Bt are shipped across oceans annually, [4] often from one end of the world to the other.
Energy commodities account for more than 5 billion tons, or over 40% of seaborne trade. Dry bulk cargo accounts for almost half the total, at around 6 billion tons.
What you may find interesting is that more recently, partially driven by geopolitical turmoil, the ton miles, which is how far each ton travels on average, has grown faster at about 6% than the tonnage shipped, growing at about 2% [7].
Now that we understand the size of the market, let’s look at what fuels these vessels
World fleet by vessel type (UNCTADstat + estimates for sub-categories, 100GT and above)
| Ship type | Number of vessels | % of fleet (count) | DWT (billion) | % of fleet (DWT) |
|---|---|---|---|---|
|
Bulk carriers |
14,600 |
13% |
1.1 |
42% |
|
Oil tankers |
12,900 |
11% |
0.7 |
27% |
|
Container ships |
7,000 |
6% |
0.4 |
15% |
|
General cargo, LNG, LPG, cruise, and ferry |
31,400 |
27% |
0.2 |
8% |
|
Other (chemical/specialized tankers, reefers, offshore supply, tugs, dredgers, etc.) |
49,700 |
43% |
0.2 |
8% |
|
Total world fleet |
115,600 |
100% |
2.5 |
100% |
Table 1: World fleet by type
2. What keeps those ships moving… primary energy
The total primary energy (also referred to as total energy supply TES) we as humans consume every year, amounts to approximately ~170,000 TWh. Approx. 25% or close to 40,000 TWh is consumed for global transportation (see Figure 1).
- Trivia on Ice: 170.000 TWh is a huge number and if, theoretically, directed at melting ice from -10C then this energy would suffice to melt a cube of ~1,900 km3 (a cube of ~12km, or ~1,700 Bt in weight) every single year [8]. Just a reminder, Greenland loses somewhere around 220 Bt each year [9].
By the way, an estimated ~60% of primary energy [10] from oil, that is about ~33,000 TWh of oil’s total of ~56,000 TWh in 2025 is used for transportation. But oil “only” makes up about 90% of transportation fuel [10], so ~36,000 to ~37,000 TWh is a good estimate for total primary energy going into transportation annually.
Note on refining: Interesting is the efficiency of crude oil refining into usable oil products such as diesel, gasoline, jet fuel, fuel oil, etc. It turns out that refining is about 90% efficient [11]. That means only about 10% of the primary energy in crude oil is used for the entire operation and 90% ends up in usable refined products mostly but not only for transportation. Of those, one can estimate of oil’s primary energy
- almost 80% ends up as road/aviation transport fuel,
- ~2% ends up as marine fuel,
- over 10% becomes other refined products,
- and ~9% is consumed operating the refineries.
Across all modes of transportation, road transport is the most dominant mode at roughly 80% of transport energy use, aviation roughly 10%, and marine also around 10% [12]. That would mean only about 2+% of total primary energy [13] is consumed for marine fuels (roughly 10% of 25% primary energy). This is a bit more than Germany’s primary energy demand. So, if we were to reduce marine fuel’s emissions by half – I dare say – it is highly unlikely that the global environmental impact would be significant, as you will see in the last section herein.
Let us now go directly to final consumption and marine or bunker fuels.
The marine fuels or the bunker fuels market spans two families, conventional and alternative:
- Conventional – Currently 90+% (Figure 2)
- (a) residual fuels (mainly used in main engines): High Sulphur Fuel Oil (HSFO, for scrubber-fitted ships), Very Low Sulphur Fuel Oil (VLSFO, 0.50% S) and Ultra Low Sulphur Fuel Oil (ULSFO, 0.10% S) used in Emission Control Areas or ECAs.
- (b) distillate fuels (mainly used in auxiliary engines): Marine Gas Oil (MGO) and Marine Diesel Oil (MDO), used in Emission Control Areas and at berth, and as main-engine fuel on smaller vessels.
- Alternative – Currently less than 10%: alternative fuels such as LNG, methanol, LPG, biofuel blends, ammonia, hydrogen.
The conventional fuel category remains overwhelmingly dominant by volume; but the alternative fuls category is where currently nearly all regulatory and investment attention appears to be directed at.
The total bunker market comprises about 325 Mln tons p.a. and has been relatively stable over the past years. Marine fuels then make up less than 10% of about 3.8 Bt of all refined oil products used annually worldwide which include diesel, gasoline, jet fuel, heavy fuel oil, marine fuels, and others. S&P Global Commodity Insights mentions that bunker consumption will rise only marginally to about 330 Mln tons by 2030, then declining toward roughly 300 Mln tons by 2050 [14] as efficiency improves and the switch to alternative fuels is expected to outpace trade growth.
Why bunker fuel? On steamships, coal for the engines was stored in dedicated compartments called bunkers (the same word used for coal storage in general, including on land, coal bunkers in buildings/rail yards). “Bunkering” meant loading coal into those compartments before a voyage. When ships switched from coal to fuel oil in the early-to-mid 20th century, the tanks storing the new liquid fuel took over the same name, “bunkers”, even though nothing was being stored in a compartment in quite the coal sense anymore. The term just carried across the fuel transition rather than being replaced, so “bunkering” now means taking on fuel oil, and “bunker fuel” means the fuel itself.
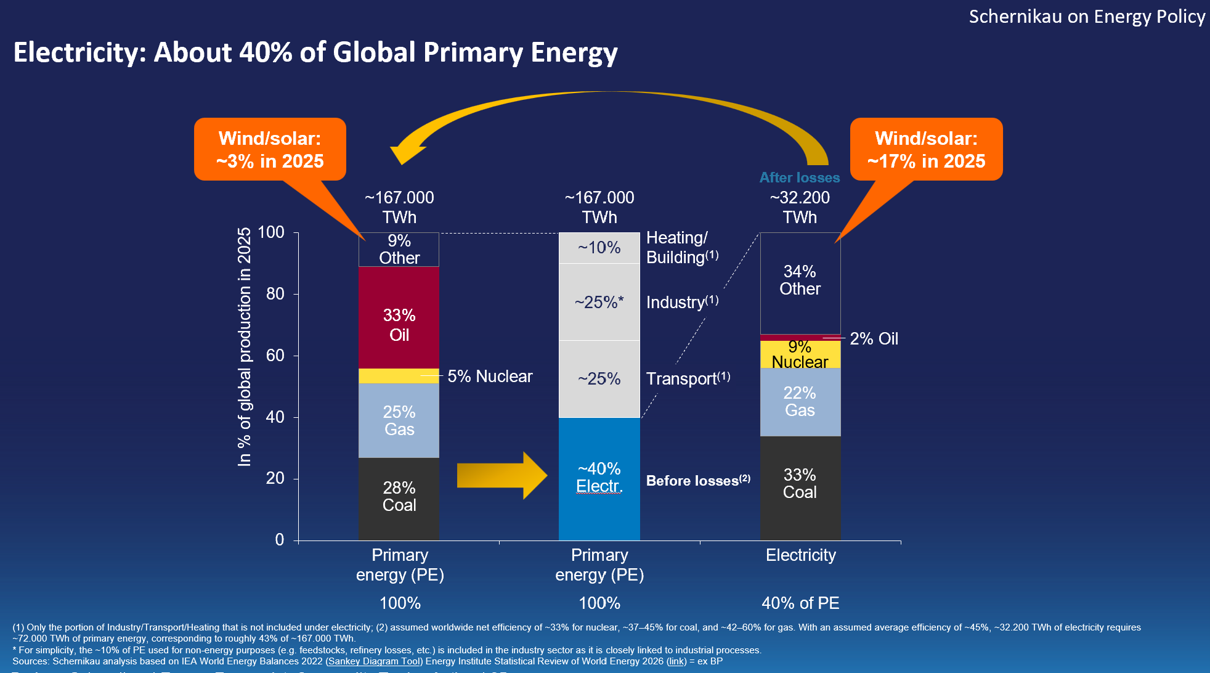
Figure 2: Global primary energy
3. One industry, competing rulebooks
Since marine fuels are largely refined oil-based products, they directly react to geopolitical circumstances, positively and negatively. What moves oil will move bunker fuel.
The conflict in the Middle East in March 2026 showed how quickly this can happen. As oil supplies and shipping routes came under pressure, in main ports like Singapore, the price of very low sulphur fuel oil (VLSFO) rose from roughly USD 500 to around USD 900 per ton.
But what really concerns the industry and causes a lot of distress are “carbon regulations (1)” targeted at “saving the climate” and doing so through envisioned “decarbonization”. The idea is to penalize CO2e emitting fuels (conventional marine fuels) with large enough monetary consequences to have the market move towards lower CO2e emitting transport solutions (alternative marine fuels). The problem is, as it so often is, that only tail-pipe emissions are considered and not the entire life cycle or system required.
The economic and environmental impact of such “carbon regulation” appears to not be fully understood (actually it is understood reasonably well but largely ignored). I covered this subject at length in a previous blog post “The Problem with the Primary Energy Fallacy”. The hope is to have synthetically produced “e-fuels” manufactured using “green” electricity to replace oil-based products and by doing so reducing greenhouse gas emissions. Under the next point we discuss this idea in more detail.
The EU Emission Trading Scheme or ETS is not only the fastest growing but probably the “strictest” of such “carbon regulations”. The EU is putting pressure on ships by calling on Europe to join the scheme starting as recent as 2024 (see box below), making this a new initiative. What is interesting is that the IMO (International Maritime Organization) has a “net-zero” framework that was in principle agreed on in Apr 2025, but it was derailed and is now subject to an “adoption vote” in Dec 2026. The IMO regulations are facing heavy US/Saudi opposition. This means, to date, there is no global “carbon regulation” for the global shipping industry.
[1] “Carbon” is often used loosely for CO2e or CO2e. That matters, because 1 t C ≈ 3.67 t CO2 and CO2e also covers other greenhouse gases such as Methane CH4 and N2O. CO2 is a photosynthesis input with a measurable fertilization effect. It makes up about 0.04% of the atmosphere. Water vapour contributes most to today’s greenhouse effect.
In the meantime, regional rules keep expanding creating a big “mess” (EU, Mediterranean, Canadian Arctic and Norwegian Sea ECAs, North-East-Atlantic ECA, etc). An unwanted consequence of this regulatory mess is that the IMO’s claim to be the shipping industry’s single global regulator, is now under threat.
Current EU ETS regulation is projected to increase shipping fuel cost by 50-100%. For example, the EU ETS bill will reach almost 10 Billion USD in 2026 for the maritime industry [15]!
Shipping is a global industry that requires one global rulebook, yet shipowners face an EU system that already imposes costs while the global framework remains under negotiation and regional environmental requirements continue to multiply.
As an example, carriers of course pass regulatory costs on to consumers through EU ETS surcharges on freight. A freight-rate guide estimates around $170 per container, or 6–7% on top of the base freight rate, for EU-linked trades [16].
A Sidenote on sulphur. In 2020, the IMO enacted regulation to reduce sulphur content of fuel from 3.50% to 0.50% resulting in most of the fuel combusted in vessels today, being of low sulphur quality (VLSFO – very low Sulphur fuel oil).
The regulation reduced sulphur pollution from ships, delivering a measurable improvement in air quality. That benefit came at a substantial economic cost, however, as switching to compliant fuel increased fuel costs by around 15–20%. [17]
The increase of global temperatures, I assume, was an unintended consequence of lowering sulphur emissions. SO2 has a strong cooling effect on the climate, both through directly reflecting incoming sunlight and by acting as cloud condensation nuclei [18]. Tselioudis et al 2025 explained the physics in their peer-review academic paper [19]. The consequences of “carbon regulation” for the marine fuel industry are not only a far higher cost compared to sulphur regulations but also that there will be no measurable positive environmental impact (see last section), contrary to what happened after IMO 2000.
EU ETS – Emissions Trading Scheme and Maritime shipping’s role
- EU ETS. The EU’s cap-and-trade carbon market has been running since 2005. A falling cap limits total emissions, and companies must surrender one allowance (EUA) per ton of CO2e emitted. EUAs are traded, so the cost moves with the market price.
- Shipping in the ETS. Shipping joined the ETS only in 2024. The shipping company (owner, or the manager formally given responsibility) surrenders allowances by 30 September of the following year. Missing allowances incur a €100/t penalty, and must still be surrendered.
- EU MRV (monitoring, reporting, and verification). Regulation (EU) 2015/757, in force since 2018. Ships over 5,000 GT calling at EU/EEA ports monitor and report fuel use, emissions, distance, time at sea and cargo. From 2025, general cargo and offshore ships of 400–5,000 GT also report.
- Verification and publication. Each annual emissions report is checked by an accredited verifier and submitted by 30 April. EMSA, the European Maritime Safety Agency, the EU agency publishes the data ship by ship.
MRV measures the tons a ship emitted; the ETS regulation translates that into payable EUR to governments.
The Maritime relevant regulation under ETS
- Shipping companies surrendered allowances for 40% of 2024 emissions and 70% of 2025 emissions. From 2026 emissions onward, the figure is 100%. Allowances for 2026 emissions are surrendered in September 2027[19].
- Methane and nitrous oxide are covered from 2026, alongside CO2 [20].
- The rule applies from 2025 to all ships over 5,000 GT calling at EU ports, regardless of flag. Required GHG-intensity cuts rise from 2% in 2025 to 80% by 2050, against the 2020 average [21].
- Voyages within the EU pay for 100% of emissions; voyages between the EU and a non-EU port pay for 50% [22].
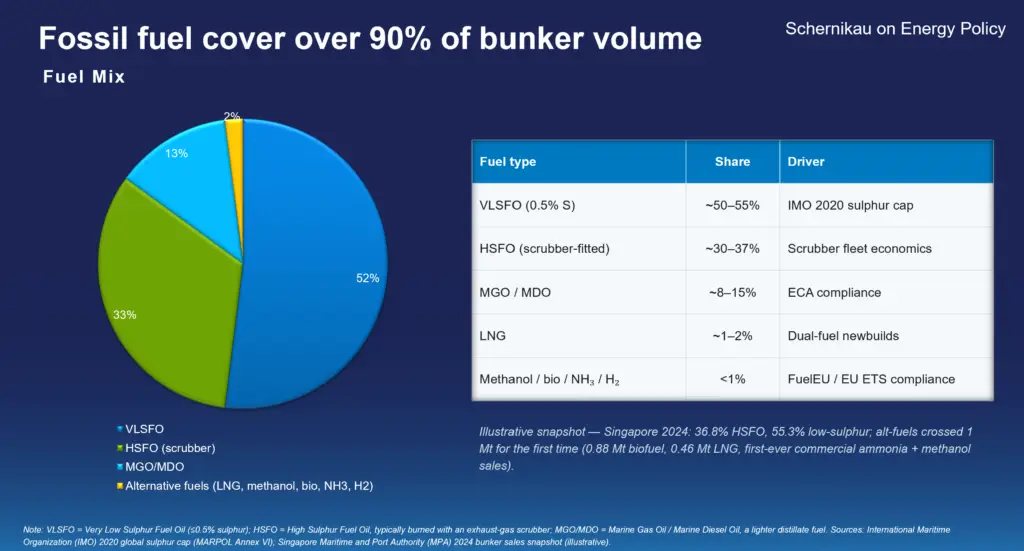
Figure 3: Fossil fuel 90% of bunker volume
4. Which ship would you order today?
Put yourself in a shipowner’s position. You are ordering a vessel that will operate for decades, but you do not know which fuel the regulations will favour, what that fuel will cost, or whether it will even be available along the routes your ship takes.
Choosing a conventional engine leaves you exposed to future regulatory costs where an alternative-fuel engine means committing capital before the fuel supply and economics are clear. A dual-fuel vessel offers flexibility, but the ability to burn another fuel does not make that fuel affordable nor does it secure availability.
Waiting is making a decision too. Ships age, maintenance continues, and opportunities to improve efficiency may be postponed along with the investment.
So, which ship would you order? This is the decision shipowners face today, and it helps explain why regulatory uncertainty matters well beyond the next fuel bill.
Figure 4: Changing the fuel changes the whole ship
5. Changing the fuel changes the whole ship
Shipowners face uncertainty, as they are resisting an illogical change and orders for vessels powered by alternative fuels have slowed in 2026. Most alternative fuel orders in the first half of 2026 were LNG (50%) and LPG/ethane ( 40+%) [23]. Methanol, ethanol, ammonia, and hydrogen had only a handful of orders. Please note that LNG- and methanol-capable ships burn conventional fuels when alternative fuel prices rise. Also, most of these LNG/LPG-capable engines are on gas carriers, which fuel themselves from their own cargo and therefore create little conventional bunker demand in the first place. Reminder, 95% of the operating fleet by tonnage and 99% by number of ships today still runs on conventional fuel.
Alternative fuels present several practical and economic challenges.
- The most obvious problem is the low energy density (Table 1, Figure 3). Methanol needs about 2.5x the tank volume of Marine Gas Oil MGO.
- The most misunderstood problem is that at life-cycle and system level the “alternative fuels” are NOT better for the environment. Too many “net-zero” electricity sources are assumed that simply don’t exist. Hydro, biomass, solar, or wind do NOT generate “net-zero” electricity (see my blog articles on hydro power here, on biomass here, and on wind and solar here) and grid-scale electricity is the most complex and most expensive form of energy.
- The economics of “alternative fuels” are not favorable. It is energy-economically impossible that an e-fuel using wind and solar as the basis (which is largely assumed and globally targeted) will be lower cost than a conventional fuel. There is insufficient hydro-power or biomass waste-power available to make a true difference in transport.
For example, “green” ammonia is not only not green, but requires 12 MWh/ton of “green net-zero” electricity that is 24/7/365 available on demand22 to industrially produce hundreds of millions of tons. “Green” ammonia from wind and solar + batteries maybe technically feasible but capital-intensive, and scaling it to global demand would take thousands of TWh/yr of dedicated generation at very low electricity costs. See my published article “Can Solar and Wind + Batteries Really Provide 24/7/365 Electricity?”
“Producing” an alternative fuel is only the beginning. Don’t forget that before a ship can use it, that fuel must be transported, stored and supplied at the ports where the vessel needs to refuel, with suitable equipment and procedures for handling it safely.
For a shipowner, the practical question is whether enough fuel will be available along the intended route, at a price that allows the vessel to remain competitive. This creates a difficult investment challenge because fuel suppliers need customers before committing to production and bunkering infrastructure and shipowners need confidence in that supply before ordering vessels that depend on it.
Here is an extract on hydrocarbon fuels illustrating the importance of carbon that “carbon regulation” is trying to eradicate, copied from our book “The Unpopular Truth… about Electricity and the Future of Energy”, Chapter 2.5 (www.unpopular-truth.com):
Because carbon adds its own significant energy to the mix, gasoline has ~3,5x higher volumetric energy density (joules per liter) than liquid hydrogen, and ~7x higher density than compressed H2
The addition of carbon transforms hydrogen from a low-density, explosive gas that will only become liquid at around -250°C (20K) into an easily-handled room temperature hydrocarbon liquid, such as gasoline, diesel, or other petroleum products (CxHxOx). These hydrocarbons have more than triple the energy density of hydrogen alone (see Kiefer 2013 for more details).
Thus, hydrocarbon fuels are convenient to produce, store, transport, and consume, while H2 is very difficult and energy-intensive to produce, handle, store, or transport for consumption, and is highly explosive. Until a means to duplicate the utility of hydrocarbon fuels in a presently unknown H2 or H-containing medium is found, hydrogen cannot solve the “renewable” energy storage or transportation problem, neither economically nor environmentally.
Since the periodic table shows that discovering a new element to replace carbon is not probable, we must invent something else to replace carbon’s role by finding ways to increase the volumetric density of H2.
“If we didn’t have carbon, we would have to invent it as the ideal tool for handling hydrogen”
A sidenote on nuclear: Nuclear propulsion is well established and holds promise for commercial shipping, although we believe widespread adoption is still many years away.
Prof. Jan Emblemsvag (NTNU, Dept. of Ocean Operations and Civil Engineering) from Norway is one of the global academic leaders on maritime shipping and nuclear propulsion specialist. He argues, and we agree, that nuclear propulsion is a possible avenue for future maritime transport, particularly for large ships [24].
In one of Emblemsvag’s recent peer-reviewed academic research papers [25] he also drew the following conclusions which are aligned with our analysis herein:
The gravimetric energy densities are orders of magnitude too low, or the thermodynamical losses are too high, for electricity to replace fossil fuel in this particular application [marine fuels]… the estimated electricity required to produce green alternative fuels is far beyond the current power system capabilities.
Energy per cubic meter, by fuel
| Fuel | Energy (GJ/m³) | % of VLSFO | Volume vs VLSFO |
|---|---|---|---|
|
VLSFO |
36.4 |
100% |
1.0× |
|
Biodiesel (FAME) |
33.3 |
91% |
1.1× |
|
LPG (propane) |
23.5 |
65% |
1.5× |
|
LNG |
23.4 |
64% |
1.6× |
|
Bio-LNG |
23.4 |
64% |
1.6× |
|
Ethanol |
21.1 |
58% |
1.7× |
|
Methanol |
15.4 |
42% |
2.5× |
|
Ammonia (liquid) |
12.7 |
35% |
2.9× |
|
Hydrogen (liquid) |
8.5 |
23% |
4.3× |
Table 2: Energy per cubic meter, by fuel

Figure 5: Energy density of different fuels
6. The future clouded by fear, and the future with clarity
What is likely to happen in a world shaped by conflict and uncertainty, with two active wars already resulting in longer voyages and limited product availability? … we will see persistently high and volatile bunker prices!
Costs also influence prices, and the three main underlying cost drivers for bunker fuel today are
- Geopolitical conflicts (i.e., oil supply, voyage time)
- Sanctions and compliance
- Environmental regulation, specifically on and around “carbon”
The maritime industry cannot invest in the most efficient ship engines if it doesn’t know what regulatory rules will apply in five years. So, ship owners will be creative carry what they can and seek to recover the cost of necessary investments through higher freight rates, ultimately adding to the prices we all pay.
… increasing the cost for the everyday citizen.
If we think straight, we would stop trying to force a switch away from the most efficient way to move goods by sea and air. We should rather invest in R&D to find more energy efficient solutions for the future of transportation fuels and shipping which may include nuclear propulsion or white-hydrogen based e-fuels. This would provide much needed investment security to ship owners, and costs would sink.
A closing thought. According to the IPCC’s own MAGICC “climate calculator” [25], if the entire world of shipping would emit 50% less CO2 every single year, the world would then genuinely reduce roughly 400 million tons of CO2e because of its maritime “decarbonization”. In such an unrealistic scenario the modeled averted temperature increase from shipping’s “decarbonization” would be ≈0.015 °C in 75 years, by the year 2100 (see below on IPCC)! Keep in mind that such a miniscule temperature increase cannot be measured and can only be modeled using disputed IPCC-sanctioned climate models fed with uncertain macro- and micro- as well as energy-economic and atmospheric physics assumptions about the world’s future.
IPCC’s MAGICC Calculator for calculating global warming
MAGICC is a simplified climate-model calculator used in IPCC assessments to estimate how different greenhouse-gas emissions pathways affect atmospheric concentrations, radiative forcing, and global temperature over time.
As per MAGICC, as a rule of thumb, genuinely and permanently removing 1 billion tons of CO2 each year for 75 years and utilizing 8-15% of global electricity to do so, would result in ≈0.035 °C less warming in 2100. Such temperature change remains undetectable and therefore can never be proven.
Using the IPCC AR6 model framework, this corresponds to roughly 7 mm of avoided sea-level rise by 2100, also not measurable. For context, the IPCC projects that by 2100 global mean sea level would be about 10 cm lower at 1.5 °C warming than at 2 °C warming, with a wide uncertainty.
MAGICC is a reduced-complexity climate model, not a general circulation model (GCM). It is widely used by IPCC, integrated assessment models IAMs, and policymakers because it is fast, transparent, and tunable. Of course, this assumes that the climate models and scenarios used to calculate are correct, which is in dispute. MAGICC assumes, the climate system behaves approximately like the mean of CMIP5 models, which is a highly biased assumption…. But for the sake of this example, let’s assume MAGICC is correct, see www.magicc.org
CO2e Emissions from large commercial ships are estimated at around 800 Mt p.a., a 50% saving would translate to about 400 Mln saved p.a. => 0,4 Bt x 0.035 °C per 1 Bt ≈ 0,014°C warming. I have not found a scientist yet who can explain to me in reasonably simple language, how such a minuscule modeled temperature change can reduce extreme weather events, without relying on even more complex models using unrealistic assumptions and more improbable scenarios.
7. Give shipowners a reason to invest!
I want us to come back to the same question I posed earlier… which ship would you order today? As we can now see, a shipowner cannot answer that confidently without knowing which rules will apply, which fuels will be available and whether the investment will make economic sense over the vessel’s working life.
The practical priority should be to improve the efficiency of shipping today while researching better options for tomorrow, including taking nuclear propulsion seriously, without assuming it is ready for widespread commercial use, and assessing alternative fuels on their full production, supply and operating requirements.
Environmental regulation should be judged by what it achieves and what it costs, because, a fuel does not become a better solution simply because a regulation makes the existing fuel more expensive. Shipping keeps the goods we depend on moving, why are we not working on giving shipowners clear, stable rules and enough room to invest in workable solutions, so that they can plan ahead?
Leave them guessing, and the cost of that uncertainty will eventually reach all of us!

Links and Resources
[1] UN Review of Maritime Transport series (link)
[2] UNCTADstat, “Merchant fleet: World fleet by flag of registration and ship type” — Core indicators, Annual (analytical), World / Number of ships, by ship type, 2019–2026 (last updated 18 Jun 2026): (link)
[3] All details in the blog article “Coal keeps the lights on” (link)
[4] Clarkson PLC. (2026). Market trends 2025. In Annual report 2025. (link)
[5] Pacific Basin Shipping Limited. (2026, March 3). 2025 annual results [Investor presentation], slide 16. Underlying data: Clarksons Research, February 2026. (link)
[6] Clarkson Research Services Limited. (2026, January 2). 2025 shipping market review. Shipping Intelligence Weekly, “2025 at a glance,” section 4: World trade. (link)
[7] UNCTAD: Staying the Course in Turbulent Waters. Review of Maritime Transport 2025. United Nations, 2025.(link)
[8] How much ice can 170,000 TWh (612 EJ) melt, starting from –10°C?
Energy required = warming ice from –10°C to 0°C + melting it at 0°C
- Specific heat of ice: c ≈ 2.1 kJ/kg·K
- Latent heat of fusion (melting, phase changing): L ≈ 334 kJ/kg (94% of total energy)
- Sensible heat (–10°C → 0°C): 2.1 kJ/kg·K × 10 K = 21 kJ/kg (6% of total energy)
- Total energy per kg: 21 + 334 = 355 kJ/kg
Energy available: 170,000 TWh = 6.12 × 10²⁰ J = 6.12 × 10¹⁷ kJ
Mass melted: m = 6.12×10¹⁷ kJ ÷ 355 kJ/kg ≈ 1.72 × 10¹⁵ kg (≈1,720 gigatonss)
Volume (ice density 917 kg/m³): V = 1.72×10¹⁵ ÷ 917 ≈ 1.88 × 10¹² m³ ≈ 1,880 km³
Equivalent cube: edge length = ∛1,880 km³ ≈ 12.3 km
Result: 170,000 TWh would warm and melt ~1,880 km³ of ice (≈1,720 Gt) — equivalent to a cube roughly 12.3 km × 12.3 km × 12.3 km.
[9] NOAA Arctic Report Card, GRACE/GRACE-FO satellite gravimetry, 2003–2024 average: −219 ± 16 Gt/yr, (link)
[10] Stanford Understand Energy Learning Hub. “Energy for Transportation.” Transport sector ≈29% of global total final energy consumption; >90% of transport energy from oil. Available at: (link)
[11] Brown, H. and Wang, M. Estimation of Energy Efficiencies of U.S. Petroleum Refineries, Argonne National Laboratory (2008 data update). Overall refinery energy efficiency = 90.8%, i.e., ~9.2% of energy input consumed as refinery fuel/loss. Available at: (link)
[12] International Energy Agency (IEA). Key World Energy Statistics 2021. p.39, “Total final consumption by sector: oil based on 2019 data: road 49.2%, aviation 8.6%, navigation 6.7%, rail 0.8%, non-energy use 16.7%, industry 7.3%, residential 5.3%, other 5.4%. Available at: (link)
[13] Calorific-value assumption for marine fuel oil (~11.25 MWh/tons, VLSFO/HSFO blend) — standard industry conversion factor, used to convert tonss to TWh
[14] S&P Global Commodity Insights, April 2023, (link)
[15] Calculation: For 2026 that number is simply put as follows: assuming 100USD/t of CO2e and 90 Mln tons of CO2e are chargeable under ETS, it would translate to around 9 Bln USD. A more detailed view with 2025 numbers is here: Ships reported 150 Mln tons of CO2e on EU-related voyages. After the 50% rule for international voyages, out-of-scope ships and derogations, 88 million tons is chargeable under the ETS. Intra-EU voyages make up 26% of total emissions but 38% of the chargeable total, because they count in full. At €87/t (US$99), close to today’s price, 2025 chargeable emissions are worth about $8.75bn (€7.7bn) at the full 100% rate that applies from 2026. Intra-EU voyages account for $3.3bn of this. At the 70% rate actually surrendered for 2025, the bill is about $6.1bn in 2025. EU MRV 2025 data; our analysis.
[16] Shipping Rates 2026, (link)
[17] Carbon Brief. “Analysis: How Low-Sulphur Shipping Rules Are Affecting Global Warming.” Carbon Brief, July 2023.(link)
[18] Tselioudis et al 2025: Contraction of the World’s Storm-Cloud Zones the Primary Contributor to the 21st Century Increase in the Earth’s Sunlight Absorption.” Geophysical Research Letters 52, no. 11 (2025): e2025GL114882. (link)
[19] European Commission, reducing emissions from the shipping sector, (link)
[20] European Commission, FAQ on maritime ETS, (link)
[21] European Commission, DG MOVE, (link)
[22] Ship & Bunker, Jan 2026, (link)
[23] Maritime Executive on DNV AFI, Jun 2026, (link)
[24] Sources for the table: C-Job Naval Architects, Ammonia as a Marine Fuel (2019), for LNG, ethanol, ammonia and hydrogen; DNV / SEA-LNG (2019) for methanol (lower heating value 19.5 MJ/kg; DNV’s figure of about 2.5 times the tank volume of MGO); US DOE Alternative Fuels Data Center for biodiesel (B100) and propane; peer-reviewed fuel-property review (2023) for VLSFO. All figures are lower heating values per cubic meter of liquid fuel. Bio-LNG is treated as equal to LNG. Figures exclude tank systems: DNV notes that with storage included, LNG has only about a third of diesel’s volumetric energy density.
[25] Emblemsvag 2025: A Study on the Limitations of Green Alternative Fuels in Global Shipping in the Foreseeable Future.” Journal of Marine Science and Engineering 13, no. 1 (2025): 79. (link)
[26] IPCC = Intergovernmental Panel on Climate Change, a UN sponsored and financed organization studying the human impact on global climate, the IPCC sanctioned MAGICC calculator can be accessed at (link)